Intuit Credit Karma

- 440.75K Reviews
- 4.7
- Downloads
- 50,000,000+
 Analysis by Appgk
I think a credit app is most useful when it helps turn a vague worry into a sensible next step. Intuit Credit Karma is built around that routine: check where your credit stands, look for changes, and decide whether there is something worth acting on. I would treat it as a handy monitoring companion, not as a substitute for a lender’s decision or a full household budget.
Following a credit check from first look to next step
I’d use the first check to establish a baseline, then treat any score movement as a prompt to inspect the report rather than as a verdict. That keeps the workflow grounded in details you can verify and makes the next step—whether that is simply monitoring or looking into an unfamiliar account—more deliberate.
Starting with the question you actually have
Most people do not open a finance app for entertainment. They may be preparing to apply for a card, trying to understand why a score changed, or simply wanting to know whether an unfamiliar account has appeared. This app is aimed at those moments. It is a free finance app from Credit Karma, LLC, and its focus is credit information alongside tools and recommendations that can help you think through possible next moves.
The app has been available since February 28, 2013, and its current version is 25.49. It is rated for Everyone and requires Android 9 or later on Android devices. It is also available on iOS. Its 4.7 average from around 3.1 million ratings and more than 50 million installs suggest it has reached a very large audience, though popularity alone does not tell you whether its recommendations fit your situation.
Getting started is straightforward in the published experience: I entered personal details, answered security questions, and reached the main screen without much fuss. That initial step is also the point to slow down and check that you are comfortable using a finance app for personal credit information. Take care to enter details accurately; a typo or an old address can make identity checks or matching records less smooth.
The first screen gives you a quick place to orient yourself rather than requiring you to interpret a pile of figures all at once. I find that useful if my goal is simply to establish a baseline. If you are checking before a major application, though, do not assume that one in-app score is exactly the number a particular lender will use. Credit decisions can depend on the lender’s own criteria and the information it reviews.
Moving from a score to a useful investigation
In my experience, the best way to use a score is as a prompt for questions, not as a grade. Credit Karma presents scores associated with TransUnion and Equifax, with weekly updates described in the app experience. Seeing information from two bureaus can help you notice that credit files are not always identical. If one view changes and another does not, that difference is a reason to inspect the underlying report rather than immediately assuming something is wrong.
News Picks to Read Next
View All News
A practical routine is to check the score, then open the report details and scan for accounts, balances, or activity you do not recognize. That order matters: the score tells you that something may have shifted, while the report can help you investigate what is behind the movement. I would avoid making a payment or closing an account just because the number looks disappointing. First understand which information is current and whether the change has a straightforward explanation.
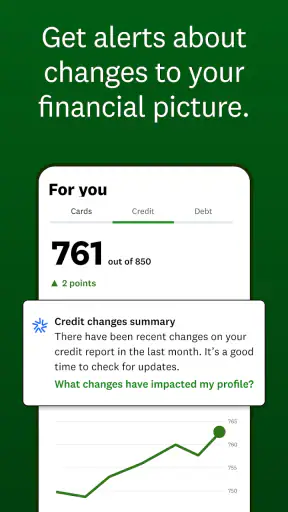
The monitoring alerts are useful as a nudge when a notable change appears, such as a new account. They do not remove the need to review the details yourself. If an alert looks unfamiliar, I would check the report promptly, compare the account information with my own records, and contact the relevant institution through a channel I already trust. An alert is a reason to investigate, not proof of fraud by itself.
Best Parts of Intuit Credit Karma
Things to Keep in Mind About Intuit Credit Karma
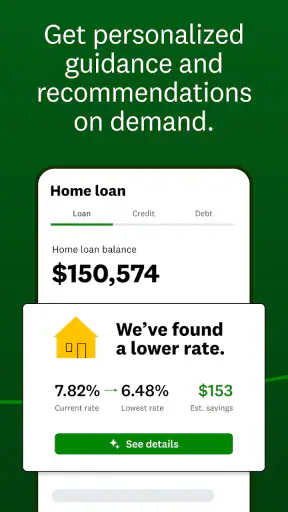
The app’s explanations around recommendations can also make financial language less intimidating. I like having context beside a suggested action, because a recommendation is easier to evaluate when I understand what it is trying to address. Still, I would treat suggestions as options to examine rather than instructions. A product that appears relevant to a credit profile may not suit a person’s budget, repayment habits, or plans.
Using the tools without letting them make the decision
The debt repayment calculator is most useful when you already know the balances and payment amounts you want to compare. I would use it to test a couple of realistic plans, then check whether the suggested monthly commitment still leaves room for essentials and irregular expenses. A faster payoff can look appealing in a calculator, but a plan that is too tight is hard to maintain. The useful result is not merely a shorter timeline; it is a payment approach you can actually keep following.
For a real-world example, imagine that I am reviewing my finances after payday and notice that a card balance is taking longer to shrink than expected. I can use the calculator to compare paying a little more toward that balance with keeping my current payment, then decide whether the difference is manageable. I would write down the plan and revisit it after a normal month, rather than treating one optimistic estimate as a promise. The tool helps make the trade-off visible; my budget still decides what is realistic.
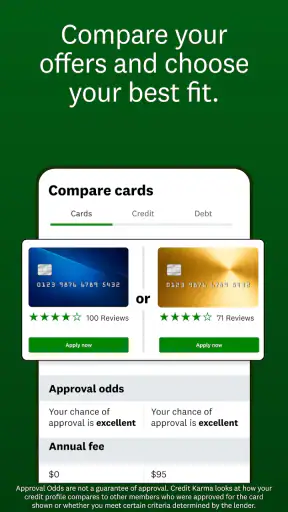
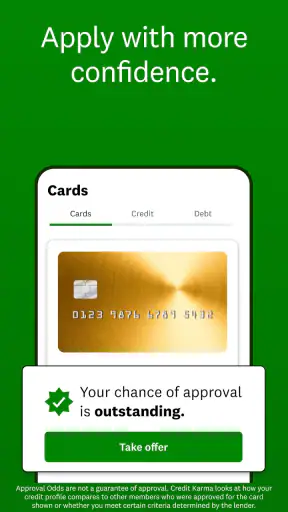
Credit card and loan recommendations are another handoff from information to possible action. They can save time compared with starting from a blank search, especially if I am exploring what kinds of products might be relevant to my profile. But a recommendation is not the same as a guarantee of approval or a complete comparison of costs. Before applying, I would read the lender’s terms carefully, consider fees and repayment obligations, and compare the offer with options from my bank or another source.
That distinction is important if you are trying to protect your credit while shopping around. Checking information in an app is different from submitting a formal application, and applications can involve lender-specific checks. I would use the recommendations to create a shortlist, then verify details directly before taking an action that could affect my finances. If you already know the product you want, a direct comparison of official lender terms may be more useful than browsing suggestions.
Where it fits among other finance options
Compared with checking a score through a bank, this app brings credit monitoring and related recommendations into one place. A bank’s own tools may be more convenient if you want to keep all your money information within an existing account, while this app is more focused on credit and potential next steps. Neither view should automatically be treated as the final word on every lender’s assessment.
Screenshots
Compared with a spreadsheet or a dedicated budgeting app, Credit Karma is not where I would go first to plan every category of household spending. Its debt calculator can help with a specific repayment question, but a budget tool is better suited to tracking regular income, bills, and flexible spending together. I would pair tools only when each has a clear job, rather than entering the same information in several places and making the routine harder than it needs to be.
It is a good fit for someone building credit, checking for unexpected report changes, or comparing possible credit products without starting from scratch. It is less suitable for someone who wants a complete budget, individualized financial planning, or a single score guaranteed to match a specific lender’s model. If your main concern is a disputed account, the app can help you notice and inspect it, but resolving the issue may require contacting the bureau or company involved.
What to keep in mind as you use it
The main friction is that a clean score screen can make credit look simpler than it is. Scores are snapshots, and a weekly update is not a live record of every financial event. Different bureaus can hold different information, and lenders can weigh details in their own ways. I would use the app to follow broad movement and spot questions, not to predict an exact approval outcome or time a major decision to a particular score change.
Recommendations also create a potential distraction. When you open an app to understand your credit, it is easy to drift into browsing cards or loans before deciding whether borrowing is necessary. My tip is to set the purpose of each visit first: monitoring, investigating a report detail, or comparing a product. If you only wanted to check a change, finish that task before considering any offer. That small boundary helps keep a useful tool from becoming an impulse-shopping prompt.
Another practical trade-off is convenience versus concentration of personal financial information. A single app can make routine checks easier, but you should still use a strong, unique password and be cautious with account access on shared devices. I would also avoid treating an alert notification as a complete explanation; open the relevant details and verify them before reacting. Those habits matter more than checking the app repeatedly.
If your report looks different from what you expected, start by checking whether the account or balance is familiar and whether the timing could explain the difference. If you still believe information is incorrect, follow the appropriate dispute process with the organization responsible for the report. Credit monitoring can point you toward a problem, but it cannot make an inaccurate record correct by itself.
A measured recommendation
After following the workflow from an initial score check through report review and possible repayment planning, I see Intuit Credit Karma as a practical starting point for staying engaged with credit. Its strongest use is helping you notice changes and turn a broad concern into a concrete question: What changed? Is it accurate? Is there an action worth taking? The combination of monitoring, explanations, a repayment calculator, and product suggestions gives many users a reason to return without requiring them to be credit experts.
I would recommend it to a friend who wants a free, approachable way to keep an eye on credit and is willing to verify important details before acting. I would not recommend relying on it alone for budgeting, debt counseling, or a prediction of what a lender will decide. Used with that boundary, it can make credit feel less opaque and help you approach the next financial step with more context. If your needs are broader, pair it with a budget method or seek guidance suited to the decision rather than expecting one app to do everything.
Getting Started with Credit Karma
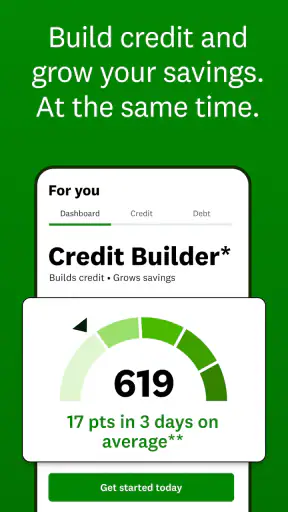
First things first, downloading the Intuit Credit Karma app is a breeze. It’s available for both Android and iOS, and I had it up and running in no time. The sign-up process was straightforward. A few personal details and a couple of security questions later, I was in.
What immediately caught my attention was the clean, user-friendly interface. Even if you’re not a tech wizard, you’ll find navigating through the app a piece of cake. And guess what? It’s totally free! No hidden charges or sneaky subscriptions here.
Features that Stand Out
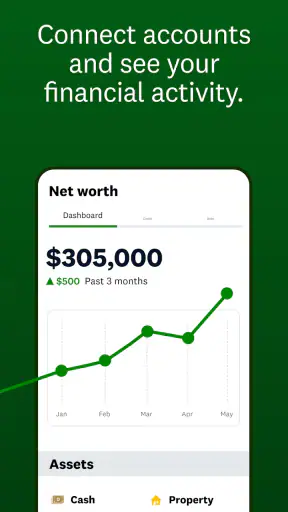
Once inside, I was greeted with my credit score, updated weekly. This isn’t just any score; it’s pulled from both TransUnion and Equifax, giving you a pretty solid overview of where you stand. It’s like getting a sneak peek at what lenders see without the hard inquiry.
The app also offers personalized recommendations on how to improve your score. Need a little help deciphering the financial jargon? No worries. Each recommendation comes with a detailed explanation, making it easier for you to take action.
I was particularly impressed with the credit report monitoring feature. It alerts you to any significant changes, like a new account being opened. It’s like having a watchdog on duty 24/7, guarding your financial health.
Exploring the Financial Tools
Now, let’s talk about the additional features that make this app a real gem. The debt repayment calculator is a game-changer. It helps you plan and manage your debt effectively, showing you how different payment strategies can impact your timeline and interest payments. It’s like having a personal finance coach cheering you on.
Another cool tool is the credit card and loan recommendations. No more endless scrolling through options that may not suit you. The app suggests cards and loans based on your credit profile, potentially saving you time and money.
Final Thoughts
In conclusion, if you’re looking for a hassle-free way to keep an eye on your credit score, the app is definitely worth checking out. It’s user-friendly, packed with useful features, and, most importantly, free. Whether you’re working on building your credit or just want to stay informed, this app has got you covered.
So, if you haven’t already, give it a try. It might just be the financial buddy you didn’t know you needed.
Intuit Credit Karma FAQ
What features does Intuit Credit Karma offer?
Intuit Credit Karma provides users with free credit scores, reports, and insights. It also offers personalized recommendations for credit cards and loans, based on your credit profile. Additionally, the app includes tools for credit monitoring, financial planning, and tax filing, making it a comprehensive financial management tool.
Is Intuit Credit Karma safe to use?
Yes, Intuit Credit Karma employs robust security measures to protect your personal information. The app uses 128-bit encryption and offers multi-factor authentication to ensure that your data remains secure. It's important to note that while no system is infallible, Credit Karma is widely regarded as a safe platform for managing credit information.
How accurate are the credit scores and reports on Intuit Credit Karma?
Intuit Credit Karma provides credit scores and reports from TransUnion and Equifax, two of the three major credit bureaus. While these scores are generally accurate, they may not always match the scores used by lenders, as different scoring models may be applied. However, they offer a reliable snapshot of your credit health.
Does using Intuit Credit Karma affect my credit score?
No, checking your credit score and reports through Intuit Credit Karma does not affect your credit score. The app performs a 'soft inquiry,' which is not visible to lenders and does not impact your score. This allows you to monitor your credit health without any negative consequences.
Are there any fees associated with Intuit Credit Karma?
Intuit Credit Karma is completely free to use. The app generates revenue through ads and referrals for financial products, but there are no hidden fees or charges for accessing your credit scores, reports, or any other features offered by the app. This makes it a cost-effective tool for managing your finances.